
Options Income Strategies: Covered Calls & Cash-Secured Puts
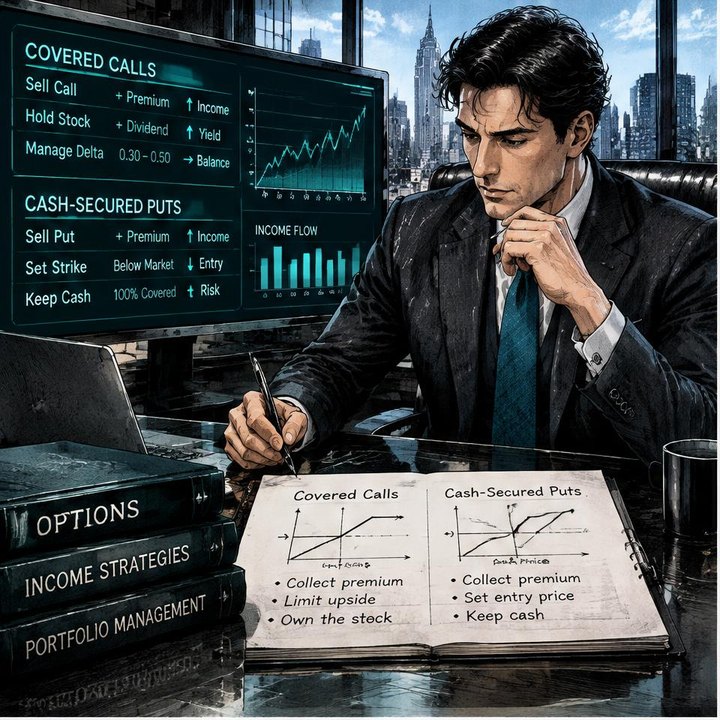
Covered calls and cash-secured puts are options income strategies that exchange some flexibility for an upfront premium. Covered calls generate cash flow from shares you already own; cash-secured puts pay you for accepting an obligation to buy shares at a chosen strike. They can help experienced stock investors structure neutral to slightly bullish positions, but neither guarantees reliable income or protects against a major decline. This article is education, not financial advice.
What Covered Calls and Cash-Secured Puts Actually Do
Options are more than speculative betting tools: they can transfer risk, hedge exposures, and create portfolio cash flow. However, comparing option premiums to collecting rent misses an important distinction: the premium compensates you for accepting a contractual obligation and market risk.
With covered calls, you sell a call against shares you own. A standard U.S. equity option contract generally represents 100 shares, although adjusted contracts can differ. If assigned, you must deliver those shares at the strike price, regardless of how high the market has moved.
With cash-secured puts, you sell a put while reserving sufficient cash to purchase the underlying shares at the strike if assigned. The obligation is to buy, even if the market price has fallen substantially below that strike.
Both positions generally suit neutral to slightly bullish expectations. Covered calls surrender upside beyond the strike; cash-secured puts can miss a rally while exposing you to downside if shares fall. At comparable strikes and expirations, their expiration payoffs can be closely related, after accounting for cash, premiums, dividends, and financing.
How They Work on a Chart and an Option Chain
Start with the stock chart, then inspect the option chain. Reversing that process encourages choosing weak companies simply because their premiums look attractive.
For a covered call, identify an area where you would genuinely accept selling your shares, perhaps near prior resistance. A strike near that area can express your exit plan, but resistance does not prevent a breakout.
For a cash-secured put, identify a purchase level supported by your valuation work and market structure. Previous support can provide context, but a support line does not limit your loss. Price can gap below both support and your strike.
Then review:
- Expiration: Shorter-dated options often have faster time decay near expiration, but also sharper changes in directional exposure.
- Implied volatility: Richer premiums typically reflect greater expected uncertainty, not a free advantage.
- Liquidity: Wide bid-ask spreads and limited trading activity can make entry, adjustment, and exit expensive.
- Events: Earnings, dividends, and company announcements can change the trade’s risk abruptly.
These strategies benefit from theta, all else equal: an option’s remaining time value tends to decay as expiration approaches. But a stock move or volatility increase can outweigh that benefit. Premium received is not automatically profit; the short option remains a liability until it expires, is closed, or is settled through assignment.
Worked Examples: From Entry to Expiration
Consider a stock you already own that is trading within an established range. You remain constructive on the business, but would willingly sell near the upper end of that range.
You sell a covered call with a strike aligned with that acceptable exit level. The premium arrives upfront, and the shares remain in your account while the call is open.
If the stock finishes below the strike at expiration and the call expires unexercised, you keep the shares and premium. If the stock rallies above the strike and you are assigned, you sell at the strike and retain the premium, but miss further upside. If the stock falls sharply, the premium offsets only part of the share-price loss.
Now consider a company you want to own, but not at its current market price. You sell a cash-secured put at a lower, acceptable purchase level and reserve the required cash.
If the put expires unexercised, you retain the premium and your cash is released from the obligation. If assigned, you purchase the shares at the strike. Your economic acquisition cost is the strike minus the premium received, before fees and taxes.
That lower effective entry is not necessarily a bargain. If the business deteriorates and the stock gaps down, you still buy at the strike and immediately hold shares worth less than you paid.
Touching the strike does not automatically trigger assignment. Exercise decisions, expiration procedures, and option style matter.
Assignment, Payoffs, and Position Management
Most U.S. listed stock options are American-style, meaning holders can exercise before expiration. A short option can therefore be assigned early. For covered calls, early assignment deserves particular attention around ex-dividend dates when an in-the-money call has little remaining time value.
Near expiration, after-hours moves and exercise instructions can also create uncertainty. Do not assume a closing price just outside the strike guarantees no assignment. Know your broker’s procedures and deadlines.
At expiration, the payoff boundaries are straightforward:
- Covered call: Maximum upside is generally the difference between the strike and your share purchase price, plus premium, before costs. A collapse in the stock can still produce a substantial loss.
- Cash-secured put: Maximum profit is the premium received. If the stock becomes worthless, the loss is the strike multiplied by the contract share count, minus premium, before costs.
Decide before entry whether you will accept assignment, buy back the option, or consider rolling. A roll closes one contract and opens another; it does not erase a loss. Even a roll for a net credit can extend exposure or increase the obligation.
Evaluate total portfolio return, including share-price changes, not premium collections alone.
Common Mistakes That Undermine Options Income
The central mistake is treating options income as dependable yield. Cash flow can recur while the portfolio loses value.
Other errors include:
- Chasing premium: Expensive options can signal distressed businesses, event risk, or unusually uncertain outcomes.
- Selling calls on untouchable holdings: If you cannot accept selling the shares, the call conflicts with your investment plan.
- Confusing willingness with capacity: Being happy to own a company does not make an oversized assignment affordable.
- Ignoring correlated exposure: Several puts can become stock positions together during a broad selloff.
- Mechanically repeating trades: Automatically selling calls after put assignment can cap recovery below your acquisition cost.
- Overlooking friction: Fees, spreads, taxes, and restricted cash affect the result.
Ask whether you would remain comfortable owning the company through a prolonged decline. That question supports due diligence; it does not replace valuation, diversification, or position limits. Our 1-on-1 Mastery program offers personalized educational guidance on developing that risk-first process.
A Short Practice Checklist
Before placing a simulated trade:
- Define your thesis and an acceptable sale or purchase price.
- Verify the contract multiplier, exercise style, expiration, and deliverable.
- Check liquidity, earnings, dividends, and buying-power requirements.
- Map flat, rally, decline, and gap scenarios.
- Set position limits and an assignment or exit plan.
- Journal total position performance, not just premium.
If your goal is to learn trading free, use the free trading course to build foundations before rehearsing these positions. Choosing the best website to learn trading—or the best trading coach for your needs—means prioritizing clear risk explanations over income promises.
Continue exploring Trade Feeld, with updates from @tradefeeld on X, @akylles on X, and @tradicators on X, alongside Instagram, YouTube, and LinkedIn. Whatever the channel, judge any options strategy by its full obligations, downside, and fit with your process—not its premium alone.
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
Breakout Trading Strategy Step by Step
Breakout trading is the art of capturing big momentum as price clears key resistance levels. Learn the exact criteria for a high-probability breakout.
Pullback Strategy: Buying Dips the Right Way
Learn how to enter a trend at a discount by identifying high-probability pullback zones.
Comments(0)
Discuss the article and share your tips.