
Earnings Options Setups: Straddles vs Spreads
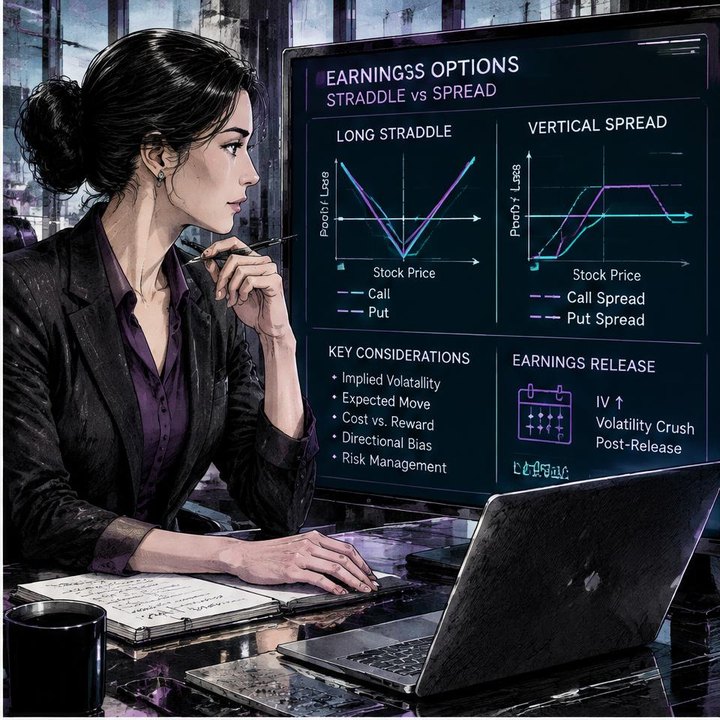
For earnings options setups, a long straddle targets a move large enough to overcome the combined option premiums, while vertical spreads express a directional view with defined risk and typically lower capital outlay than buying the comparable standalone option. This guide helps experienced stock and options traders evaluate earnings trading, understand volatility crush, and choose structures based on expected movement, pricing, and maximum loss—not direction alone. It is education, not financial advice.
What Earnings Volatility Crush Actually Means
Earnings releases are among the most consequential scheduled volatility events for individual stocks. Results, guidance, and management commentary can reset expectations before traders have a practical opportunity to react.
Before the announcement, options often carry elevated implied volatility, or IV: the volatility implied by their market prices. IV frequently rises as earnings approach, although that pattern is not guaranteed. After the report resolves uncertainty, IV usually falls sharply. Traders call this volatility crush.
That decline reduces an option’s extrinsic value, all else equal. It does not mean every option falls in price: a sufficiently large favorable stock move can increase intrinsic value enough to outweigh the crush.
The central distinction is realized movement versus movement already priced into options. Correctly predicting an earnings beat or the stock’s direction is insufficient if the option premium demanded a stronger reaction.
How Straddles and Vertical Spreads Work
A long straddle combines a purchased call and purchased put with the same strike and expiration, commonly near the current stock price. It avoids choosing an initial direction, but it is not a cost-free bet on movement.
At expiration:
- Maximum loss is the combined premium paid, plus trading costs.
- The upper breakeven is the strike plus that combined premium per share.
- The lower breakeven is the strike minus that premium.
- Upside profit is theoretically unlimited; downside profit is bounded because a stock cannot fall below zero.
Before expiration, value also depends on remaining time, IV, and execution prices. Expiration breakevens are therefore not exact targets for a next-session exit. A straddle begins approximately direction-neutral near the money, but its directional exposure changes as the stock moves.
A vertical spread combines a long and short option of the same type and expiration at different strikes.
- A bullish call debit spread buys a lower-strike call and sells a higher-strike call.
- A bearish put debit spread buys a higher-strike put and sells a lower-strike put.
- A bullish put credit spread sells a higher-strike put and buys a lower-strike put.
- A bearish call credit spread sells a lower-strike call and buys a higher-strike call.
For debit spreads, maximum expiration loss is the debit paid; maximum profit is strike width minus debit. For credit spreads, maximum expiration profit is the credit received; maximum loss is strike width minus credit. Apply the contract multiplier and account for costs.
Spreads offset some volatility exposure because one option is bought and another sold. They do not eliminate volatility crush, and net IV sensitivity varies with price, strikes, and time remaining.
Reading the Chart and Option Chain Together
Start with the earnings schedule. Confirm whether the announcement occurs before the open or after the close, and whether the chosen expiration includes the event.
Then mark the stock’s pre-earnings range, prior session’s high and low, and nearby support or resistance. These levels help describe possible reactions, but an overnight gap can jump past them without offering an executable entry or stop.
Next, inspect the option chain:
- Compare expirations that include earnings with those that do not.
- Check bid-ask spreads and quoted size on both legs.
- Compare the cost of an at-the-money straddle with plausible post-report movement.
- Examine whether your proposed spread’s short strike caps profit before your chart target.
The at-the-money straddle premium is often used as a rough move reference. It is not a precise forecast, guaranteed range, or automatically a probability interval.
On the chart, distinguish an initial gap from follow-through. Price may break above the prior day’s high, then retreat into the pre-earnings range. A headline that looks bullish can therefore produce a disappointing option exit.
The Trade Feeld Terminal can help you examine historical earnings reactions and build context. Historical moves are reference points, not promises about the next announcement.
Worked Example: Right Direction, Different Outcomes
Consider a stock consolidating below resistance before earnings. A trader expects a bullish reaction but recognizes that disappointing guidance could instead produce a sharp decline.
The trader compares a near-the-money long straddle with a bullish call debit spread. Both expire after the report.
With the straddle, the trader pays for movement in either direction. Earnings arrive, and the stock gaps above resistance. The call gains intrinsic value, but the put loses value and IV falls across the event-sensitive options.
If the rally is modest relative to the premium paid, the combined position can still lose money. The bullish reaction happened, yet it did not compensate for buying two expensive options. A substantially larger move could instead make the winning call outweigh the losing put and the volatility crush.
With the call debit spread, the trader buys a call and sells a higher-strike call. Selling that second option lowers the initial debit and offsets part of the volatility exposure. The same rally may produce a more favorable outcome relative to the capital committed, but profit is capped.
If price rallies beyond the short strike, the spread cannot capture unlimited additional upside. Before expiration, it may also trade below its maximum expiration value.
A bullish put credit spread offers another expression: profit can come from the stock remaining above the short strike. However, a sufficiently adverse gap can push the position toward maximum loss. Collecting elevated earnings premium is compensation for risk, not free income.
Common Mistakes That Distort the Trade
Treating all earnings trades as low-probability, high-payoff bets. Expensive long straddles can fit that profile, but credit spreads may have frequent smaller gains and occasional larger losses. Probability depends on strikes, pricing, and the actual distribution of outcomes.
Assuming lower capital means lower danger. A spread may cost less than a standalone option, yet concentrating more contracts can erase that advantage.
Relying on a stock stop overnight. A stop cannot guarantee an exit at its trigger price after a gap, and options may not trade when the earnings news arrives.
Ignoring assignment and expiration mechanics. American-style short options can be assigned early. Near expiration, exercise decisions and after-hours movement can leave unexpected stock exposure. Defined expiration payoff does not remove operational risk, particularly if one leg is closed or exercised separately.
Sizing from conviction instead of loss capacity. Know the maximum contractual loss before release, including the multiplier and costs. Stress-test that loss across correlated positions rather than evaluating each trade in isolation.
A Short Practice Checklist
Before placing a simulated earnings trade:
- Confirm announcement timing, expiration, and contract specifications.
- State whether the thesis concerns direction, magnitude, or overpriced movement.
- Compare the straddle premium with chart scenarios and historical reactions.
- Calculate maximum loss, maximum profit where capped, and expiration breakevens.
- Plan exits, execution limits, and assignment handling.
- Review stock movement and IV changes separately after the event.
If you search “learn trading free,” the useful question is whether the material teaches repeatable decisions. The best website to learn trading should explain uncertainty; the best trading coach should challenge assumptions, not promise outcomes. Continue with the free trading course or explore the Trader Program.
For further learning, visit Trade Feeld, YouTube, and Instagram, or follow @tradefeeld, @akylles, @tradicators, and LinkedIn.
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
Breakout Trading Strategy Step by Step
Breakout trading is the art of capturing big momentum as price clears key resistance levels. Learn the exact criteria for a high-probability breakout.
Pullback Strategy: Buying Dips the Right Way
Learn how to enter a trend at a discount by identifying high-probability pullback zones.
Comments(0)
Discuss the article and share your tips.