
Risk Framework: The 1% Rule, R-Multiples & Drawdown Limits
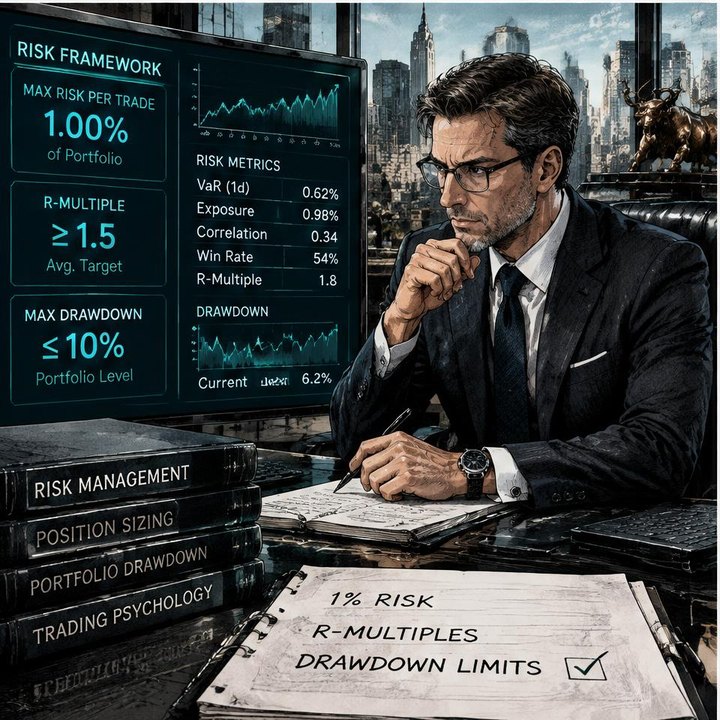
Risk management is the framework that keeps a trading account alive: use the 1% rule to cap planned risk per trade, measure results with R-multiples, and enforce drawdown limits before losses become emotional decisions. This framework helps intermediate traders in stocks, indices, crypto, and forex turn a trading idea into a controlled exposure. It cannot guarantee profits or prevent every loss, but it makes survival a deliberate part of your process.
What the Risk Framework Actually Controls
An entry tells you where to participate. A risk framework tells you how much exposure to take, where the idea becomes invalid, and when to stop trading altogether.
Professional trading puts risk management ahead of the search for a perfect entry. Even a strong setup can fail. Your job is not to eliminate uncertainty; it is to keep any ordinary failure from threatening your ability to take the next valid opportunity.
The framework has three connected parts:
- The 1% rule: Never allocate more than 1% of total account equity as planned risk on a single trade.
- R-multiples: Measure gains and losses against each trade’s initial risk.
- Drawdown limits: Stop trading when account losses reach predefined boundaries.
These are educational rules, not personalized financial advice. They also have an important limitation: planned risk is not guaranteed maximum loss. Gaps, slippage, thin liquidity, and execution failures can push a realized loss beyond the amount you intended.
Applying the 1% Rule to a Real Chart
Start with current account equity, not buying power or the amount your broker allows you to borrow. Under the 1% rule, a $10,000 account has a maximum planned risk budget of $100 per trade. That is a ceiling, not a target you must use.
Next, identify where the trade becomes invalid on the chart. Suppose price breaks above the prior day’s high, then pulls back toward the breakout area. Your trading plan might require that area to hold before entering.
Choose the stop based on the setup’s invalidation point and normal market movement. Do not choose an arbitrary tight stop simply to afford a larger position.
The basic calculation is:
Position size = permitted cash risk ÷ cash loss per unit if the stop executes as planned.
For shares, the price distance between entry and stop determines the basic risk per share. For other instruments, translate that distance correctly:
- Indices: Check the contract multiplier or cash value of each point for the product traded.
- Forex: Convert the stop distance using pip value, lot size, and account currency.
- Crypto: Check whether exposure is spot or derivatives, including contract specifications and liquidation conditions.
Allow for commissions, spreads, and a reasonable execution buffer within the risk budget. Round size down to the permitted trading increment. If the smallest available position is too large, skip the trade.
Leverage changes margin requirements, not the underlying loss generated by a price move. A position can require little margin while exposing the account to substantial risk.
A Worked Example: From Setup to R-Multiple
Consider the same $10,000 account and $100 maximum planned risk.
Price breaks above the prior day’s high and holds the breakout area on a pullback. Before entering, the trader identifies a stop below the area whose failure would invalidate the setup.
The trader calculates the cash loss per share or contract at that stop, accounts for expected trading costs, and selects a position whose planned loss stays within $100. A wider stop means a smaller position; a narrower valid stop permits a larger one. The risk budget does not expand because the setup looks attractive.
Next, the trader identifies a possible exit near overhead resistance. If the planned reward is $300 against $100 of initial risk, the opportunity offers a 3R reward relative to risk. That is a planned outcome, not a promised result.
If the trade ultimately produces a net $300 profit, its realized result is 3R. If it loses the full initial risk amount, it loses one R. If execution is worse than expected, the loss can exceed one R.
Realized R-multiple = net trade profit or loss ÷ initial cash risk.
Keep the initial risk denominator fixed. Moving a stop or taking partial profits does not rewrite the original risk. Record the combined net outcome of all exits against that original amount.
R-multiples make different trade sizes comparable. They also explain why a high win rate is not enough: frequent small wins can be overwhelmed by occasional large losses. What matters is positive expectancy after costs, considering win frequency, average winning R, and average losing R together.
Drawdown Limits: When Trading Must Stop
Drawdown is a decline in account equity from a reference level, commonly a previous equity peak. Daily and weekly loss limits are related controls that use defined session or week reference values.
The framework here uses firm boundaries:
- If the account loses 2% in a day, stop trading.
- If the account loses 5% in a week, take a break.
Define these limits before trading begins. A practical policy measures daily losses against starting-day equity and weekly losses against starting-week equity, adjusted for deposits and withdrawals. Include trading costs and unrealized losses so an open losing position cannot hide a breach.
Also write down what happens to existing positions when a limit is reached. A conservative policy cancels pending entries and closes remaining exposure, subject to market availability and execution conditions.
Neither boundary guarantees an exact maximum loss. Rapid moves can carry equity through a limit before you can act.
A separate peak-to-trough account drawdown boundary can trigger a broader strategy review. Set it in advance rather than improvising after losses.
Reaching a limit is not permission to switch markets or increase size. Review execution, market conditions, and rule compliance before resuming. The purpose is to prevent revenge trading and emotional account damage.
Common Mistakes That Undermine the Rules
Treating 1% as automatically safe. Several correlated positions can behave like one larger bet. Stock positions may share sector exposure; forex trades may repeat the same currency bet. Set an aggregate exposure limit as well as a per-trade cap.
Widening the stop after entry. This increases risk beyond the approved amount. A failed setup is not repaired by giving it more room.
Confusing a target with an edge. A large advertised R-multiple means little if the target is unrealistic or rarely reached.
Ignoring costs and execution. A chart-based reward estimate is not a net result. Record what actually happened.
Focusing only on win rate. Risk management matters more than a flattering percentage of winning trades. It does not create an edge by itself, but it helps prevent losses from destroying one.
Your Practice Checklist and Next Steps
Before each trade:
- Confirm current equity and available risk budget.
- Define the entry, invalidation point, and exit logic.
- Calculate size using instrument specifications and costs.
- Check correlated exposure and remaining drawdown allowance.
- Record initial cash risk for later R-multiple measurement.
Afterward, log net results, execution differences, and rule compliance.
If you want to learn trading free, use the free trading course. When comparing the best website to learn trading or the best trading coach for your needs, prioritize clear risk instruction over profit promises. Our Trader Program provides the risk management templates and spreadsheets discussed here.
Continue learning through Trade Feeld, @tradefeeld, @akylles, @tradicators, Instagram, YouTube, and LinkedIn.
A disciplined trader aims to survive market cycles, not get rich overnight.
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
Breakout Trading Strategy Step by Step
Breakout trading is the art of capturing big momentum as price clears key resistance levels. Learn the exact criteria for a high-probability breakout.
Pullback Strategy: Buying Dips the Right Way
Learn how to enter a trend at a discount by identifying high-probability pullback zones.
Comments(0)
Discuss the article and share your tips.