
How to Read a Balance Sheet: Assets, Liabilities, and Equity
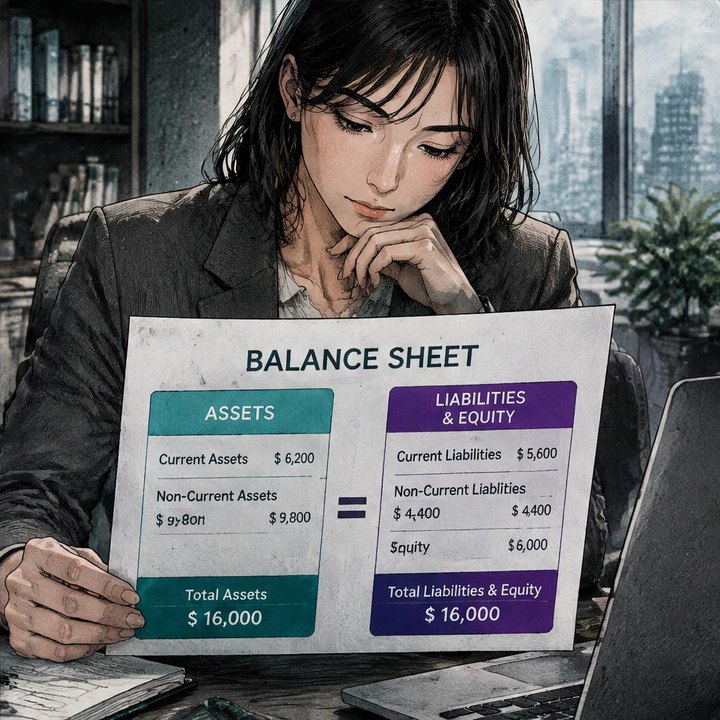
To read a balance sheet, start with assets, then compare them with liabilities and shareholders’ equity. This financial statement shows what a company owns, what it owes, and the owners’ remaining accounting stake at a specific point in time. For beginners studying stocks, options, or bonds, balance sheet analysis helps assess liquidity, debt pressure, and financial resilience before interpreting a market move.
What a Balance Sheet Shows—and What It Does Not
A balance sheet is a frozen frame of a company’s finances. Unlike the income statement, which measures performance over a period, it reports balances on a particular reporting date.
Its foundation is the accounting equation:
Assets = Liabilities + Shareholders’ Equity
Every recorded asset is matched by a creditor’s claim or an owner’s accounting interest. Liabilities are broader than borrowed money: they also include unpaid supplier bills, taxes owed, and other obligations. Equity includes money contributed by shareholders and profits retained in the business.
The equation always balances, but that does not mean the company is financially healthy. A business can have substantial assets while struggling to pay bills because those assets are difficult to sell.
Nor does a balance sheet tell you exactly what a company is worth. Accounting values can differ from market values, and the statement does not capture every source of future earning power.
Assets and Liabilities: Read the Timing First
Assets are resources the company controls. They are often presented in order of liquidity, meaning how readily they can become cash, although presentation varies.
- Current assets are cash and resources expected to be converted into cash, sold, or consumed within one year or the normal operating cycle. Examples include accounts receivable, inventory, and prepaid expenses.
- Non-current assets support operations over longer periods. These include property, plant, and equipment, long-term investments, and intangible assets such as patents or acquired brands.
Cash and cash equivalents deserve early attention because they provide a financial safety net. But check whether cash is restricted or needed for everyday operations. Receivables depend on customers paying, while inventory may require discounts before it sells.
Liabilities are debts and other obligations:
- Current liabilities generally fall due within one year or the operating cycle. They include accounts payable, short-term borrowings, taxes payable, and the current portion of long-term debt.
- Non-current liabilities fall due further into the future. Examples include long-term bonds and the longer-term portion of lease obligations.
Match timing rather than simply comparing totals. A factory may be valuable, but it cannot necessarily fund a supplier payment due soon.
Shareholders’ Equity, Liquidity, and Solvency
Shareholders’ equity is the residual accounting interest after liabilities are deducted from assets. It commonly includes contributed capital and retained earnings, reduced by items such as treasury shares.
Retained earnings represent accumulated profits kept in the business rather than distributed as dividends, adjusted for losses and other relevant accounting entries. They are not a separate cash reserve.
Equity is sometimes described as what owners would receive if all assets were sold and debts paid. That is only an accounting starting point: actual sale proceeds, liquidation costs, and creditor claims can produce a very different outcome.
Two useful distinctions guide analysis:
- Liquidity is the ability to meet near-term obligations.
- Solvency is the ability to sustain obligations over the longer term.
The current ratio = Current Assets ÷ Current Liabilities measures short-term coverage. A result above one means recorded current assets exceed current liabilities, but asset quality still matters.
The debt-to-equity ratio = Debt ÷ Shareholders’ Equity compares borrowing with the owners’ accounting base. Check the definition of debt: providers may include different obligations. Negative or very small equity can make this ratio misleading. Compare similar businesses rather than assuming one threshold suits every industry.
How Balance Sheets Connect to Market Moves
A balance sheet does not generate a chart entry signal. It helps explain the financial risks behind price movements, especially around earnings releases, refinancing announcements, or changes in funding conditions.
Suppose price breaks above the prior day’s high after a results release. Improving cash reserves and reduced near-term borrowing might support the market’s positive interpretation. Alternatively, the price move might reflect stronger sales guidance despite a deteriorating balance sheet. Read the full release rather than attributing the move to one figure.
For stocks, financial resilience can influence expectations about dividends, buybacks, acquisitions, or new share issuance. For bonds, liquidity and solvency affect repayment risk. Options traders should remember that balance sheet analysis does not replace studying implied volatility, expiration, or contract liquidity.
In our Alpha Club, “fortress balance sheets” describes businesses with substantial financial flexibility, often including significantly more cash than debt. Such flexibility can support investment during downturns, but it does not guarantee a rising share price or continued payouts.
A Worked Example: Follow the Cash Behind the Totals
Consider a hypothetical retailer whose latest balance sheet shows higher current assets than its previous statement. At first glance, its current ratio appears stronger.
Now examine the components. Cash has fallen, inventory has risen, and customers owe more through receivables. Meanwhile, a borrowing previously classified as long-term is approaching repayment and has moved into current liabilities.
The interpretation changes:
- More current assets do not necessarily mean more immediately available cash.
- Rising inventory could reflect expansion, seasonal stocking, or products selling slowly.
- Higher receivables could reflect stronger sales or slower collections.
- An approaching debt maturity increases the importance of available cash and refinancing arrangements.
Next, check the cash flow statement for cash generated by operations and read the notes for repayment terms and inventory policies.
Compare that retailer with a peer holding more unrestricted cash and fewer approaching repayments. The peer may have greater financial flexibility, but its shares are not automatically better value. Balance sheet strength and market valuation are separate questions.
Common Beginner Mistakes
- Confusing liabilities with debt. Supplier bills are liabilities, but they are not usually included in a narrow interest-bearing debt measure.
- Treating book equity as market value. Share prices reflect expectations as well as recorded assets and obligations.
- Assuming cash-rich means risk-free. Cash consumption, operating losses, restrictions, and future commitments still matter.
- Reading one reporting date in isolation. Seasonal businesses can look unusually strong or weak depending on when the snapshot was taken.
- Calling a low-P/E stock a bargain. Heavy borrowing or weak cash generation can create a value trap.
- Ignoring the notes. Debt maturities, covenants, leases, and accounting policies can change the meaning of headline totals.
A Short Balance Sheet Practice Checklist
Before reviewing a company on the Trade Feeld Terminal:
- Confirm the reporting date, currency, and units.
- Check that assets equal liabilities plus equity.
- Separate current assets from long-term resources.
- Compare available cash with approaching obligations.
- Calculate the current ratio and inspect its components.
- Review debt-to-equity using a consistent debt definition.
- Compare prior periods and industry peers.
- Cross-check the income statement, cash flow statement, and notes.
If you want to learn trading free, use this checklist with published company reports. When choosing the best website to learn trading, prioritize clear explanations and repeatable practice over promised results.
Continue learning with Trade Feeld, @tradefeeld on X, @akylles on X, @tradicators on X, Instagram, YouTube, and LinkedIn.
This material is educational, not financial advice.
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
How Companies Actually Make Money: The Core of Fundamental Analysis
Understanding the primary revenue models and cost structures that drive corporate profitability is the first step in fundamental analysis.
What Are Financial Statements? A Beginner's Guide to Corporate Data
Financial statements are the official records of a company's financial activities, providing a snapshot of its health and performance.
Comments(0)
Discuss the article and share your tips.