
How Companies Actually Make Money: The Core of Fundamental Analysis
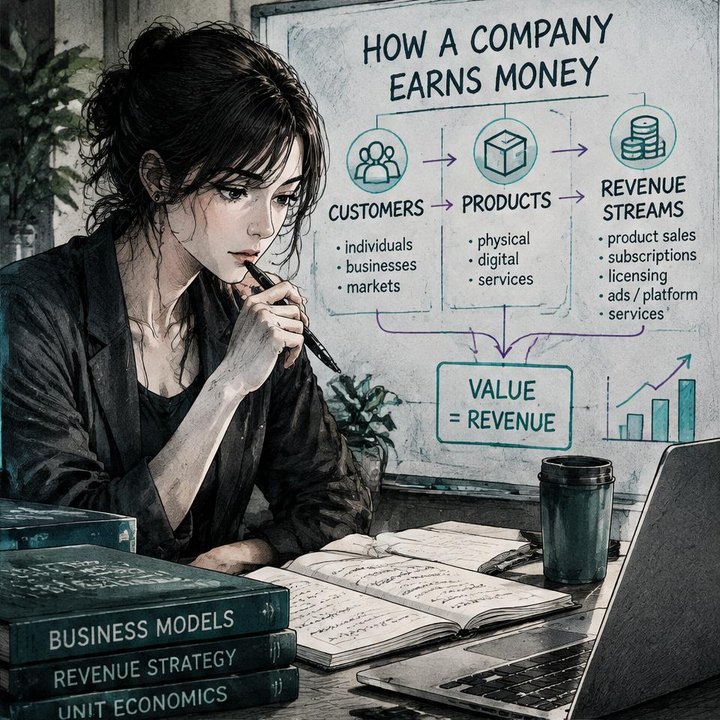
Companies make money by selling products, providing services, charging subscriptions, or earning fees from advertisers and transactions. They become profitable when those revenue streams cover the costs of delivering their offering and running the business. Understanding that conversion from sales to profit is the core of fundamental analysis. It helps beginner stock, options, and index traders assess business health rather than relying only on price movements.
Revenue vs. Profit: Follow the Income Statement
A company creates value for customers and captures part of that value as revenue. Operating revenue comes from its primary business activities, such as selling groceries or providing cloud services. Revenue is the “top line” of the income statement, which reports financial performance over a particular period.
Revenue is not necessarily cash received during that period. A business may recognize a sale before its customer pays. Equally, an advance payment may become revenue gradually as the company delivers its service.
The main steps from revenue to profit are:
- Revenue: Income generated from selling products or services, before deducting expenses.
- Gross profit: Revenue minus cost of goods sold, or COGS. Service businesses often call these direct expenses “cost of revenue.”
- Operating income: Gross profit minus operating expenses, including administration, sales and marketing, and research and development.
- Net income: The “bottom line” after interest, taxes, and other non-operating income or expenses.
Net income contributes to shareholders’ equity, but it is not a pile of cash automatically available for distribution. Companies may need cash for equipment, inventory, debt repayments, or expansion.
When using the Trade Feeld Terminal, distinguish between revenue growth and improving profitability. Higher sales show expansion; better margins indicate that the company retains more profit from each unit of revenue. Profit can also grow simply because sales rise, without any improvement in efficiency.
The Main Business Models and Their Costs
Most companies combine several business models rather than relying entirely on one.
Product sales: Businesses sell physical or digital items. Apple sells iPhones; Ford sells trucks. Revenue depends on selling prices, sales volume, and the mix of products sold. Manufacturing, materials, distribution, returns, and unsold inventory can all affect profitability.
Service fees: Consulting firms and law offices charge for expertise, projects, or employees’ time. Staff compensation is often a major cost. Growth may require hiring more people, and profitability depends partly on keeping those employees productively engaged.
Subscriptions: Customers pay repeatedly for continued access. Netflix sells entertainment subscriptions, while Microsoft offers subscription software alongside other products and services. Software as a Service, or SaaS, is one subscription category, not a label for every subscription business. Recurring revenue can improve predictability, but cancellations, discounts, and customer acquisition costs still matter.
Advertising: Google and Meta attract audiences and charge advertisers to reach them. Attention creates the commercial opportunity. Revenue depends on advertiser demand, audience engagement, and the effectiveness of ad placement. Infrastructure, content moderation, and product development remain real costs.
Other models include transaction fees, licensing, royalties, and lending. Banks and insurers need sector-specific analysis because their income statements differ from those of manufacturers or retailers.
Cost structures explain why equally large businesses can produce very different profits. Software often has relatively low costs for serving additional customers, supporting high gross margins. However, hosting, support, and computing can still be substantial. Grocery retailers must purchase the goods they sell, so their gross margins are typically much thinner.
Fixed costs, such as office rent, change slowly as sales move. Variable costs, such as materials, generally rise with activity. When revenue grows faster than operating expenses, operating leverage can lift operating income. The same mechanism can magnify weakness when sales fall.
How Business Results Appear on a Market Chart
A chart shows changes in market prices, not the income statement itself. Fundamental analysis helps explain why market participants might reassess a company.
Imagine a retailer reports rising sales but weaker gross profit because it used discounts to clear inventory. Its share price could fall despite headline growth if investors expected healthier margins. Another company might report modest sales growth but stronger operating income because overhead grew more slowly.
On a chart, an earnings announcement may coincide with a gap higher or lower, increased trading volume, or a move through a previous trading range. Those movements do not prove that one accounting figure caused the reaction. Guidance, valuation, interest rates, and broader market conditions also influence prices.
Compare the results with prior periods and market expectations. A strong business can have a falling share price if expectations were too optimistic or its valuation was demanding.
For options traders, understanding the business is only part of the task: implied volatility, time decay, and contract terms also affect outcomes. For index traders, earnings trends among heavily weighted companies can influence the index, although one company’s results do not describe the whole market.
A Worked Example: From Subscription Sales to Cash
Consider a hypothetical software company selling subscriptions to business customers.
It adds customers and sells broader packages to existing users, increasing revenue. First, it subtracts the direct costs of providing the service, including hosting and customer support classified as cost of revenue. What remains is gross profit.
Next, it pays developers, sales staff, and administrative employees. These operating expenses reduce gross profit to operating income. If subscription revenue grows while these expenses increase more slowly, operating income may improve faster than sales.
The company then accounts for interest, taxes, and any other non-operating items to arrive at net income.
Finally, examine cash flow. Customers might pay subscriptions upfront, improving cash receipts before all that revenue is recognized. Alternatively, unpaid customer invoices might leave cash generation weaker than reported earnings suggest. Equipment purchases also consume cash without necessarily becoming an immediate income-statement expense.
The lesson is to trace the whole chain: customer demand, revenue quality, direct costs, overhead, bottom-line profit, and cash generation.
Common Mistakes When Assessing Profitability
- Treating growth as proof of health. Sales gained through heavy discounting or expensive promotions may not generate attractive profits.
- Assuming recurring means guaranteed. Subscribers can cancel, reduce spending, or switch providers. Diversified revenue streams can improve resilience, but their quality matters more than their number.
- Comparing unlike businesses. A grocery retailer’s margins should not be judged against a software company’s without considering their different economics.
- Overinterpreting spending. High research spending may support innovation but does not guarantee successful products. High marketing spending may reflect expansion rather than difficulty retaining customers.
- Ignoring unusual items. An asset sale or tax benefit can lift net income without improving the core business.
- Confusing education with prediction. Searches for “learn trading free,” the “best website to learn trading,” or the “best trading coach” should lead to clear methods and risk awareness, not promises of reliable returns.
A Short Practice Checklist
Choose a company and use its financial statements to answer:
- What does it sell, and who pays?
- Which revenue streams are recurring, seasonal, or dependent on a single product?
- What are its largest direct costs?
- Are gross profit and operating income keeping pace with revenue?
- Do interest, taxes, or unusual items explain changes in net income?
- Does operating cash flow support the earnings story?
- What expectations might already be reflected in the share price?
Use comparable periods, especially for seasonal businesses. The free Seekers plan offers tools to help explore these core metrics.
This is an educational framework, not financial advice. Its purpose is to connect price activity with how a business actually earns, spends, and retains money.
Follow Trade Feeld
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
What Are Financial Statements? A Beginner's Guide to Corporate Data
Financial statements are the official records of a company's financial activities, providing a snapshot of its health and performance.
How to Read a Balance Sheet: Assets, Liabilities, and Equity
The balance sheet provides a snapshot of a company's financial health by listing everything it owns and everything it owes.
Comments(0)
Discuss the article and share your tips.