
What Are Financial Statements? A Beginner's Guide to Corporate Data
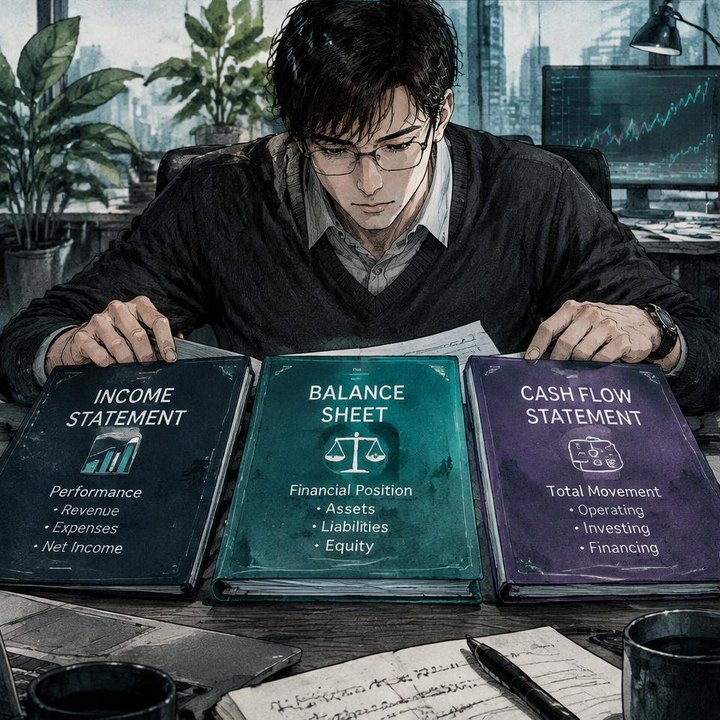
Financial statements are the official records of a company’s financial activities, showing what it owns, what it owes, how much it earns, and how cash moves through the business. They help beginner stock, options, and bond traders understand corporate health and performance rather than rely on price charts alone. This guide explains the main statements, where to find them, and how to connect them with market action.
The Three Main Financial Statements
Financial statements are standardized scorecards, but each answers a different question. Read them together rather than treating any one figure as the whole story.
- Balance Sheet: What does the company own and owe at a specific point in time? Assets include cash, inventory, and property. Liabilities include loans, supplier bills, and other obligations. Shareholders’ equity is the accounting value left after subtracting liabilities from assets. The basic relationship is assets = liabilities + equity.
- Income Statement: How did the company perform over a quarter or year? It reports revenue, expenses, and net income or loss. Earnings per share, or EPS, expresses earnings attributable to common shareholders on a per-share basis. Diluted EPS also accounts for potential additional shares under accounting rules.
- Cash Flow Statement: Where did cash come from, and where did it go? It separates operating activities, such as collecting customer payments, from investing activities, such as buying equipment, and financing activities, such as borrowing or repaying debt.
Profit and cash are not interchangeable. A company may recognize a sale before the customer pays, increasing earnings without immediately increasing cash.
The statements also connect. Net income feeds into operating cash flow through adjustments, while the ending cash balance connects to the balance sheet. Notes explain accounting policies and details that headline tables leave out. Continue with How to Read a Balance Sheet for a closer look at assets, liabilities, and equity.
Where to Find Them: 10-K, 10-Q, and SEC Filings
In the United States, the Securities and Exchange Commission requires domestic public reporting companies to submit regular SEC filings. These disclosures make financial information publicly accessible, although foreign issuers and some other companies use different forms.
The 10-K is the comprehensive annual filing. It includes a business description, risk factors, audited financial statements, accompanying notes, and Management’s Discussion and Analysis, usually shortened to MD&A. That discussion explains management’s view of results, liquidity, and important business developments.
An annual report distributed to shareholders may include the 10-K or present it alongside additional material. The terms are closely related, but the documents are not always identical.
The 10-Q is the quarterly report filed for the first three fiscal quarters. It provides condensed interim statements, MD&A, and updates to relevant disclosures. The fiscal year’s final quarter is covered through the annual reporting process rather than a separate 10-Q.
The audit distinction matters: annual financial statements in a 10-K are audited by an independent accounting firm. Interim statements in a 10-Q are generally unaudited, although they undergo an independent accountant’s review. An audit provides reasonable assurance against material misstatement, not a guarantee of perfect accuracy or business success.
Find original documents through the SEC’s EDGAR database or a company’s investor-relations page. Check the reporting period and whether figures use dollars, thousands, or millions.
How Financial Statements Connect to a Real Market Chart
Financial results influence expectations about future earnings, cash generation, and debt repayment. Those expectations help shape market prices, but they do not determine every short-term move.
During earnings season, companies often publish an earnings release before filing the full quarterly report. Prices may therefore react before the 10-Q appears. Management guidance, conference-call commentary, interest rates, and broader market conditions can also influence that reaction.
Imagine a stock breaks above the prior day’s high after an earnings announcement. The chart shows buying pressure; the financial statements help explain its possible foundation. Rising revenue, improving operating profit, and stronger operating cash flow may support the business story. A profit increase caused mainly by selling an asset deserves a different interpretation.
Even strong results can accompany a falling share price if investors expected more.
The connection differs by instrument:
- Stocks: Traders examine growth, profitability, financial strength, and valuation.
- Options: Earnings events can affect both the underlying stock and implied volatility. Correctly anticipating direction does not guarantee an option profit.
- Bonds: Cash generation, interest costs, debt maturities, and liquidity help investors assess repayment risk.
In our Trader Program, the emphasis is on combining technical setups with fundamental understanding. A breakout alongside mounting debt and weakening cash flow deserves scrutiny, not an automatic conclusion.
A Worked Example: Better Earnings, Weaker Cash
Consider a fictional equipment manufacturer whose stock rises after it announces higher revenue and EPS. Start with the income statement: sales increased, but a gain from selling a building also contributed to profit. The headline improvement therefore does not come entirely from selling equipment.
Next, examine the cash flow statement. Operating cash flow weakened while accounts receivable increased. This means more reported sales remain uncollected. It could reflect ordinary payment timing, changing customer terms, or collection difficulties; the figures alone do not establish the cause.
Then read the balance sheet. Cash declined, inventory grew, and more borrowing is due in the near term. Those developments raise questions about liquidity even though the company remained profitable.
Finally, consult the notes and MD&A. Look for explanations of customer payment timing, inventory accumulation, and how management expects to meet debt obligations.
The lesson is not that the price rise must reverse. It is that an EPS beat does not, by itself, prove sustainable improvement. The statements reveal questions a chart cannot answer.
Common Beginner Mistakes
Reading only the headline. Revenue and EPS matter, but margins, cash flow, debt, and the notes provide necessary context. Distinguish recurring business performance from one-time gains.
Comparing mismatched periods. A seasonal business may naturally sell more in one quarter than another. Compare the same quarter across years and review the longer trend. Remember that a 10-Q cash flow statement typically covers the fiscal year to date, not just the latest quarter.
Assuming cash alone proves safety. Compare available cash with upcoming debt, operating needs, and spending commitments. There is no universal cash balance that guarantees survival through a difficult year.
Treating adjusted earnings as interchangeable with accounting earnings. Management’s adjusted measures may exclude meaningful costs. Read the reconciliation to the standard accounting measure.
Confusing business quality with an attractive trade. A healthy company can already have optimistic expectations reflected in its price. Financial statements describe reported performance; they do not promise future returns.
A Short Practice Checklist
Choose one company and work through this routine:
- Open its latest 10-K and 10-Q; confirm the periods and units.
- Compare revenue and operating profit with comparable earlier periods.
- Compare net income with operating cash flow.
- Review cash, debt, and upcoming repayment obligations.
- Read relevant notes, risk factors, and MD&A.
- Mark the earnings release on a chart and describe the reaction without assuming its cause.
The Trade Feeld Terminal can help you view aggregated, visualized figures; verify important details against original filings.
If you search “learn trading free” or “best website to learn trading,” prioritize lessons that teach document checks over predictions. Explore Trade Feeld and educational updates from @tradefeeld, @akylles, and @tradicators, plus Instagram, YouTube, and LinkedIn.
This material is educational, not financial advice.
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
How Companies Actually Make Money: The Core of Fundamental Analysis
Understanding the primary revenue models and cost structures that drive corporate profitability is the first step in fundamental analysis.
How to Read a Balance Sheet: Assets, Liabilities, and Equity
The balance sheet provides a snapshot of a company's financial health by listing everything it owns and everything it owes.
Comments(0)
Discuss the article and share your tips.