
Valuation Basics: DCF and Multiples Made Simple
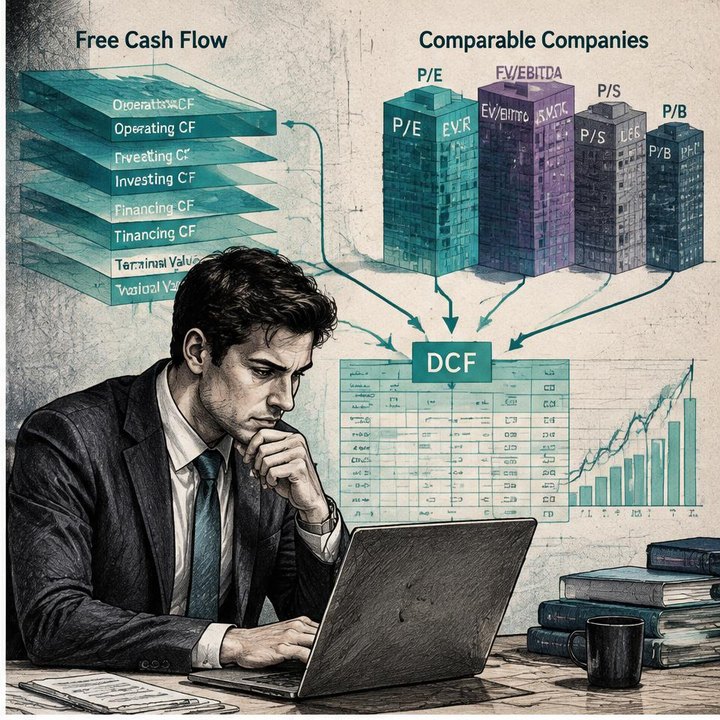
Valuation basics come down to two approaches: estimating a company’s future cash generation with discounted cash flow, or comparing its price with similar businesses using valuation multiples. Both help stock traders distinguish market price from estimated intrinsic value. For intermediate traders, including those using options on stocks, understanding DCF and multiples provides a framework for judging expectations, identifying possible mispricing, and recognizing when “cheap” may be misleading.
What valuation measures: price versus intrinsic value
Price is what buyers and sellers agree on now. Intrinsic value is an estimate of a company’s underlying worth based on the cash it can generate for investors in the future. It is sometimes called its “true” value, but nobody can observe that figure directly.
A fundamental trader looks for a meaningful difference between price and estimated value. However, that difference is not automatically an opportunity: the valuation might be wrong, or the market might take much longer than expected to recognize it.
The two main approaches answer different questions:
- Discounted cash flow: What is this business worth given its expected cash flows and risk?
- Relative valuation: How much are investors paying for comparable businesses?
DCF anchors valuation in business economics. Multiples anchor it in market comparisons. Using both can reveal assumptions that either method alone might hide.
How a DCF turns future cash into today’s value
A dollar received today is generally worth more than a dollar promised far into the future. Today’s money can be invested, while future payments involve waiting and uncertainty. A DCF accounts for this by discounting expected cash flows back to their present value.
Although often described as valuing future profits, DCF uses cash flow, not simply accounting earnings. A profitable business can still consume cash if it needs substantial investment in equipment, inventory, or customer credit.
An enterprise DCF typically follows these steps:
- Forecast revenue, operating margins, and taxes over an explicit period, often extending several years.
- Estimate reinvestment needs, including capital expenditure and changes in working capital.
- Calculate free cash flow available to the business’s capital providers.
- Discount those cash flows using an appropriate rate.
- Add a discounted terminal value for cash flows beyond the forecast period.
For free cash flow to the firm, the discount rate is usually WACC, or weighted average cost of capital. WACC combines the required returns of equity investors and lenders, reflecting the financing mix and the tax treatment of debt. Equity-only cash flows instead require a cost-of-equity discount rate.
Terminal value captures the business’s value after the detailed forecast ends. Common approaches assume sustainable perpetual growth or apply an exit multiple. Neither eliminates uncertainty: perpetual growth must remain economically plausible, while an exit multiple introduces a market-comparison assumption.
The result is enterprise value. Subtract debt and other relevant claims, add excess cash and non-operating assets where appropriate, then divide the resulting equity value by diluted shares to estimate value per share.
How multiples work in a live market
Valuation multiples compress a market valuation into a ratio. Common examples include:
- P/E: Share price divided by earnings per share. Useful when earnings are positive and reasonably representative.
- P/S: Equity market value divided by revenue. Sometimes used when earnings are negative, but it ignores profitability and can obscure financing differences.
- EV/EBITDA: Enterprise value divided by earnings before interest, taxes, depreciation, and amortization. Useful for comparing operating businesses with different debt levels, although EBITDA ignores capital expenditure and working-capital needs.
Enterprise value generally combines equity value and debt, subtracts cash, and adjusts for other relevant claims. Match enterprise value with metrics belonging to all capital providers, and equity value with metrics belonging to shareholders.
Imagine a cloud software stock trading at a lower revenue multiple than another cloud company. It might be undervalued—or it might deserve the discount because of slower growth, weaker retention, lower margins, or greater dilution.
On a price chart, valuation provides context rather than an entry signal. After earnings, a stock may fall because management reduces its outlook. The lower price does not necessarily mean better value: expected earnings or cash flows may have deteriorated even faster.
Similarly, a price breakout does not establish that a stock is fundamentally cheap. Check whether the move reflects stronger forecasts, a higher valuation multiple, or both.
A worked example: comparing two software businesses
Consider two hypothetical subscription software companies serving similar customers. One trades at a lower revenue multiple, making it appear cheaper at first glance.
Start by checking comparability. Suppose the lower-multiple business needs more sales spending to retain customers and invests heavily in product development. Its peer converts more revenue into free cash flow. The multiple gap may therefore reflect differences in business quality rather than mispricing.
Next, build a DCF for the lower-multiple company. Forecast subscription revenue, estimate operating costs, and account for taxes and reinvestment. Discount the resulting free cash flows and terminal value, then reconcile enterprise value to equity value.
Instead of relying on one forecast, create cautious, central, and optimistic cases. In the cautious case, growth slows and margins remain pressured. In the optimistic case, customer retention improves and cash conversion strengthens.
Compare that valuation range with the market price and peer multiples. If apparent cheapness disappears under modestly less favorable assumptions, the thesis is fragile. If both approaches suggest a discount under defensible assumptions, the business merits further research—not an automatic trade.
Common mistakes and the margin of safety
DCF can be rigorous without being precise. Small changes in growth, margins, WACC, or terminal assumptions can produce large valuation changes, especially when much of the estimated value lies far in the future.
Avoid these common mistakes:
- Treating a spreadsheet output as fact. Use sensitivity analysis and valuation ranges.
- Mixing measurement periods. Compare trailing multiples with trailing multiples, and forward estimates with consistently defined forward estimates.
- Ignoring unusual earnings. Asset sales, restructuring charges, and cyclical peaks can distort P/E.
- Assuming peers are fairly valued. An entire sector can be expensive.
- Treating historical averages as fixed fair value. Growth prospects, interest rates, leverage, and business quality change.
- Ignoring dilution or debt. Business value and shareholder value are not interchangeable.
A margin of safety means requiring a meaningful discount to conservatively estimated value. It creates room for forecasting error, but does not guarantee protection from losses.
For options traders, stock valuation is only part of the picture. An apparently undervalued stock can remain cheap beyond an option’s expiration. Implied volatility, time decay, liquidity, and contract terms also affect the outcome.
A short valuation practice checklist
Before interpreting a valuation:
- Identify the business’s main cash-flow drivers.
- Choose genuinely comparable peers.
- Check debt, cash, diluted shares, and accounting adjustments.
- Build multiple scenarios and test terminal assumptions.
- Separate valuation from trade timing and risk management.
In our Trader Program, we teach comparisons using the Trade Feeld Terminal, including reviewing a stock’s five-year average P/E. Historical context is a starting point, not a verdict.
If you want to learn trading free, judge any “best website to learn trading” claim by the clarity of its assumptions and exercises. Continue with Trade Feeld, its X updates, Instagram, and YouTube, alongside @akylles, @tradicators, and LinkedIn.
This material is educational, not financial advice.
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
How Companies Actually Make Money: The Core of Fundamental Analysis
Understanding the primary revenue models and cost structures that drive corporate profitability is the first step in fundamental analysis.
What Are Financial Statements? A Beginner's Guide to Corporate Data
Financial statements are the official records of a company's financial activities, providing a snapshot of its health and performance.
Comments(0)
Discuss the article and share your tips.