
How to Read a Cash Flow Statement: Following the Money
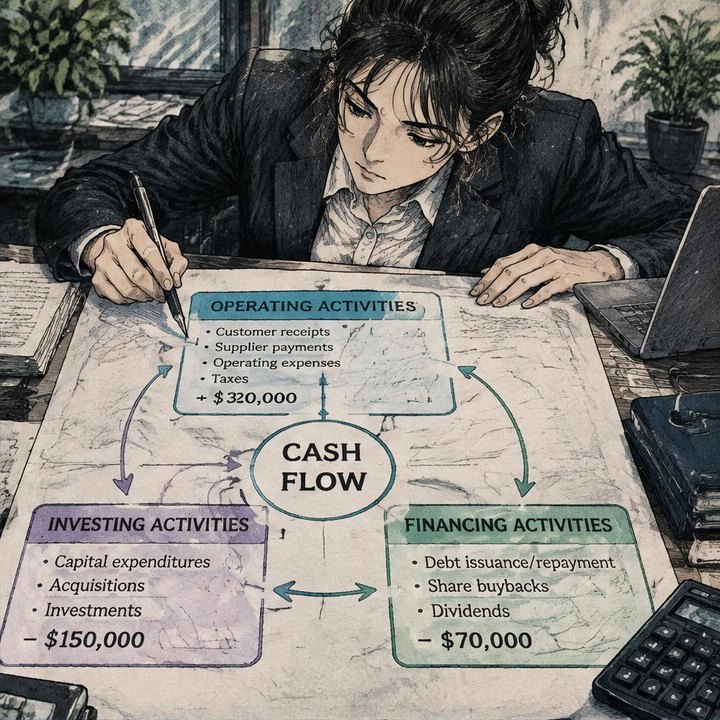
To read a cash flow statement, separate cash generated by the business from cash spent on investments and cash raised from lenders or shareholders, then reconcile those movements with the ending cash balance. The cash flow statement helps intermediate stock and options traders assess earnings quality, liquidity, and funding needs. Profit depends on accounting judgments; following the money reveals whether reported earnings translate into usable cash.
What the Cash Flow Statement Actually Shows
The income statement measures revenue and expenses. The balance sheet shows assets, liabilities, and equity at a point in time. The cash flow statement connects reporting periods by explaining changes in cash and cash equivalents.
That distinction matters because accrual accounting records revenue when it is earned and expenses when they are incurred, not necessarily when money changes hands. A product shipment may qualify as revenue when control transfers to the customer, even if payment comes later. Profit can therefore rise without an immediate increase in cash.
Cash provides an important reality check, but the statement is not an infallible lie detector. Payment timing, acquisitions, and accounting classifications can affect the picture. Read it alongside the other statements and accompanying notes.
Liquidity also involves more than the closing cash balance. Consider upcoming obligations, restricted cash, and access to financing.
The Three Sections: Operations, Investing, and Financing
Operating cash flow shows cash generated or consumed by core business activities. Under the common indirect presentation, it starts with net income, adjusts for non-cash items such as depreciation, and accounts for changes in operating working capital.
Watch these adjustments:
- Increasing accounts receivable generally uses cash relative to reported earnings: customers have not paid yet.
- Increasing inventory generally consumes cash: money is tied up in unsold goods.
- Increasing accounts payable generally preserves cash temporarily: suppliers have not yet been paid.
Some companies use the direct method, showing customer receipts and operating payments instead. The underlying question remains the same: does the business collect more cash than it spends on operations?
Investing cash flow tracks purchases and sales of long-term assets and investments. Buying equipment, building a factory, or acquiring another company typically creates an outflow. Selling assets creates an inflow. Negative investing cash flow is not automatically bad; it may reflect productive expansion.
Financing cash flow records transactions with lenders and shareholders. Issuing debt or shares brings cash in. Repaying borrowings, paying dividends, and repurchasing shares sends cash out.
Classification rules differ across accounting frameworks, particularly for interest and dividends. Check the company’s policies before comparing peers.
Together, these sections explain the movement from beginning to ending cash, with exchange-rate effects and other reconciling items where applicable. A growing cash balance funded by borrowing means something different from one funded by customer collections.
A Worked Example: Following Profit Into Free Cash Flow
Consider a hypothetical manufacturer reporting higher sales and net income. Its share price initially rises after the earnings release.
Start with operating activities. Depreciation is added back because it reduced accounting profit without requiring a current-period cash payment. However, receivables have increased because customers are taking longer to pay. Inventory has also grown as the manufacturer prepares for expected demand.
Those working-capital outflows outweigh the improvement in profit, leaving operating cash flow weaker. That does not prove misconduct. The inventory build might support future sales, while delayed collections might reverse next quarter. The notes and subsequent reports help distinguish temporary timing from deterioration.
Next, inspect investing activities. The manufacturer has purchased production equipment. This is capital expenditure, or CapEx, covering both maintenance and expansion of long-lived assets.
The common calculation is:
Free cash flow = Operating cash flow − Capital expenditures
Use CapEx as a positive amount in this formula, even when purchases appear as a negative cash-flow line.
Free cash flow measures cash remaining after operating cash needs and capital expenditures. It is not literally cash left after every possible expense or obligation: acquisitions, debt principal repayments, and shareholder distributions generally sit outside this calculation.
In this example, equipment spending leaves free cash flow negative. Financing activities then show new borrowing, which allows the company to finish the period with more cash despite its weak internal cash generation.
The lesson is to trace the source of the cash, not merely celebrate its growth. Strong, durable FCF can support reinvestment, debt reduction, dividends, or buybacks. That flexibility explains its appeal in fundamental research, including discussions in our Alpha Club, without guaranteeing resilience in every market.
Connecting Cash Flow to the Stock Chart
Cash flow provides fundamental context, not a standalone entry signal. On the Trade Feeld Terminal, compare operating cash flow, net income, and capital expenditure over several reporting periods. Use comparable periods and check whether displayed figures are quarterly, year-to-date, or trailing totals.
Then connect the filing to observable market behavior. Suppose price breaks above the prior day’s high after an earnings announcement but later falls back into its previous range. If the report also shows weak collections and heavy financing needs, those findings may help explain investors’ concern. They do not establish why every participant sold.
Conversely, stronger cash conversion may support a favorable reassessment, but price can still fall if expectations were higher or guidance deteriorates.
For options traders, cash-flow analysis informs the underlying company thesis. It does not determine whether a contract is attractively priced. Implied volatility, time decay, expiration, and bid-ask spreads remain separate considerations. A correct fundamental assessment can still accompany an unfavorable options outcome.
Common Mistakes That Distort the Reading
- Treating operating cash flow above net income as proof of quality. Consistent cash conversion is encouraging, but depreciation, stock-based compensation, and working-capital timing can inflate the comparison. Stock-based compensation is non-cash in the reconciliation but can dilute shareholders.
- Assuming negative operating cash flow proves accounting tricks. Persistent shortfalls deserve scrutiny, especially alongside reported profits. However, seasonality, growth, and collection timing can also explain them.
- Calling all investment spending wasteful. Distinguish maintenance from expansion, while recognizing that companies may not disclose a clean split.
- Ignoring temporary cash boosts. Delaying supplier payments or reducing inventory can improve cash flow without improving underlying demand.
- Comparing inconsistent FCF definitions. Free cash flow is not a standardized accounting subtotal. Read the reconciliation for company-defined adjustments.
- Looking at one quarter alone. Compare equivalent seasonal periods and longer trends, particularly when filings present cumulative year-to-date cash flows.
A Short Practice Checklist
Before drawing a conclusion:
- Identify the reporting period and reconcile opening and closing cash.
- Compare operating cash flow with net income across several periods.
- Explain the largest receivables, inventory, and payables movements.
- Locate CapEx and calculate consistently defined free cash flow.
- Separate internally generated cash from borrowing, share issuance, and asset sales.
- Check debt maturities, restrictions, and the market’s expectations.
If you search “learn trading free” or “best website to learn trading,” prioritize exercises using complete filings over isolated ratios. Our 1-on-1 Mastery sessions offer deeper practice in examining these discrepancies.
Continue with Trade Feeld, @tradefeeld on X, @akylles on X, @tradicators on X, Instagram, YouTube, and LinkedIn.
This framework is educational, not financial advice.
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
How Companies Actually Make Money: The Core of Fundamental Analysis
Understanding the primary revenue models and cost structures that drive corporate profitability is the first step in fundamental analysis.
What Are Financial Statements? A Beginner's Guide to Corporate Data
Financial statements are the official records of a company's financial activities, providing a snapshot of its health and performance.
Comments(0)
Discuss the article and share your tips.