
Key Financial Ratios Every Trader Should Know
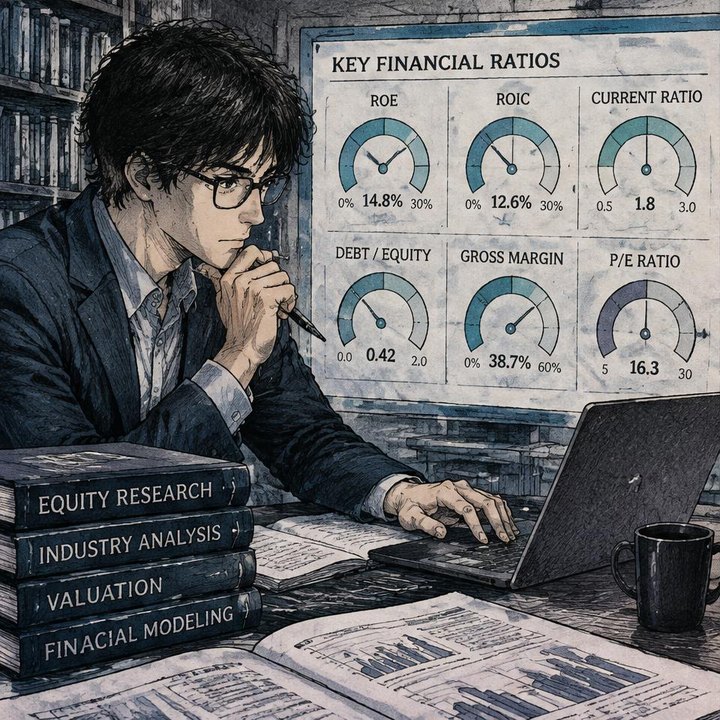
The key financial ratios every trader should know are the P/E ratio, EV/EBITDA, Return on Equity, operating margin, Debt-to-Equity, and current ratio. Together, they help intermediate stock, options, and index traders assess valuation, profitability, leverage, and liquidity. Financial ratios put headline numbers into context, making companies of different sizes easier to compare—but meaningful comparisons still require attention to industry, accounting choices, and the business cycle.
What Financial Ratios Tell You—and What They Don’t
A large profit does not automatically mean a business is attractive. You need to know how much revenue, capital, and borrowing were required to produce it. Ratios connect these figures so you can judge financial performance rather than size alone.
They fall into three useful groups:
- Valuation ratios describe what investors pay relative to earnings or another financial measure.
- Profitability ratios show how efficiently a business turns sales or shareholder capital into profit.
- Leverage and liquidity ratios help identify financial obligations and the resources available to meet them.
Ratios standardize comparisons, but they do not make every industry directly comparable. A utility, software company, and retailer have different capital requirements and operating models. Start with similar businesses, then compare each company with its own history.
These measures support research, not automatic “buy” or “avoid” decisions. They are educational tools, not financial advice or standalone trading signals.
Valuation: Understanding P/E and EV/EBITDA
P/E ratio = Share price / Earnings per share
The P/E ratio shows how much investors are paying for each unit of annual earnings. A trailing P/E uses reported earnings, while a forward P/E uses forecasts. Always check which version you are comparing.
High-growth technology businesses often command higher multiples than mature utilities because investors anticipate faster earnings growth. That premium is not automatically justified: growth expectations can disappoint, and changes in interest rates can affect what investors will pay.
A low P/E can indicate an overlooked business, but it can also reflect deteriorating prospects. For cyclical companies, unusually strong earnings can make the ratio look cheapest near the top of the earnings cycle. When earnings are negative, P/E generally becomes unsuitable for valuation comparisons.
EV/EBITDA = Enterprise value / Earnings before interest, taxes, depreciation, and amortization
Enterprise value typically includes market capitalization, debt, preferred equity, and noncontrolling interests, less cash and cash equivalents. It captures more of the financing structure than share price alone.
EV/EBITDA is widely used in acquisition analysis and comparisons between companies with different debt levels. It offers a broader perspective than P/E, rather than being universally superior.
Importantly, EBITDA is not operating income or cash flow. It excludes depreciation and amortization, and it does not account for capital expenditure or working-capital needs. A business requiring expensive equipment replacement can look attractive on EV/EBITDA while generating limited cash. It is also generally less useful for banks, where financing is central to operations.
Profitability and Financial Strength: ROE, Margins, and Debt
ROE = Net income / Average shareholders’ equity
Return on Equity measures how effectively a company generates profit from its shareholders’ accounting equity. Using average equity helps align the balance-sheet denominator with earnings generated throughout the period.
Consistently strong ROE can suggest efficient management or a competitive advantage. However, borrowing and share buybacks can reduce equity and mechanically raise ROE. Very small or negative equity can make the measure misleading.
Operating margin = Operating income / Revenue
Operating margin shows how much revenue remains after operating expenses, before interest and taxes. Rising margins may reflect pricing power, better cost control, or operating efficiencies.
Other profit margins add context. Gross margin focuses on revenue after direct production or service costs, while net margin includes interest, taxes, and other bottom-line effects. Compare equivalent measures and investigate whether improvements are recurring.
Debt-to-Equity = Total debt / Shareholders’ equity
The debt to equity ratio measures borrowing relative to the equity cushion. Higher leverage can amplify shareholder gains when conditions are favorable, but it also increases exposure to interest costs, refinancing pressure, and business downturns.
Check the data provider’s definition: some measures use interest-bearing debt, while others use total liabilities. Review debt maturities and interest coverage alongside the ratio.
Current ratio = Current assets / Current liabilities
This measures short-term liquidity rather than long-term solvency. Current assets exceeding current liabilities suggest a balance-sheet cushion, not a guarantee that bills will be paid. Inventory may sell slowly, customers may delay payment, and obligations may fall due before cash arrives.
How Ratios Connect to Charts and Market Reactions
Ratios provide business context; charts show how market participants respond. Neither replaces the other.
Around earnings announcements, a company may report stronger profits while its shares decline because expectations were higher still. Conversely, weak current results may accompany a rally if investors see improving prospects.
Consider a price break above the prior day’s high after an earnings release. Before treating that move as meaningful, examine whether:
- Earnings strength came from operating improvement or a one-off item.
- Margins and management’s outlook support the market’s interpretation.
- The price increase has already expanded the valuation multiple.
- Sector performance and trading volume support the move.
For options traders, sound fundamentals do not guarantee a profitable option position. Expiration, implied volatility, and the size and timing of the underlying move remain critical.
For index traders, aggregate valuation can provide context, but index composition matters. An index dominated by higher-multiple sectors should not be compared mechanically with one concentrated in mature businesses.
A Worked Comparison—and Common Interpretation Mistakes
Imagine two listed businesses in the same industry. The first trades at a lower P/E, which initially suggests better value. Closer inspection shows declining operating margins, elevated borrowing, and earnings boosted by a nonrecurring gain.
The second has a higher P/E but steadier margins, less borrowing, and ROE supported by recurring profits rather than a shrinking equity base.
Next, compare EV/EBITDA. Including debt may narrow the apparent valuation gap. Then examine cash generation: heavy equipment spending could weaken the second company’s apparent advantage.
The exercise does not identify a guaranteed winner. It shows why a valuation difference needs an explanation before it becomes a trading thesis.
Common mistakes include:
- Mixing reporting periods: comparing trailing earnings with forward estimates.
- Treating adjusted figures as equivalent: companies may exclude different costs.
- Assuming high ROE proves a moat: leverage can inflate it.
- Equating cheapness with a catalyst: undervaluation can persist.
- Ignoring stale data: price changes continuously, while financial statements update periodically.
A Short Ratio Scorecard to Practice
Use the Trade Feeld Terminal to organize your research, while checking reporting periods and definitions against company disclosures. Build a repeatable scorecard:
- Select genuinely comparable industry peers.
- Record P/E, EV/EBITDA, ROE, operating margin, Debt-to-Equity, and current ratio.
- Compare each measure with peers and the company’s history.
- Flag unusual earnings, accounting changes, and debt maturities.
- Write what could justify the valuation—and what would challenge it.
- Separate the fundamental thesis from chart entry criteria and risk limits.
The Trader Program offers a structured setting for developing this research process. If your goal is to learn trading free, practice the same scorecard using publicly available reports. When evaluating the best website to learn trading, prioritize clear definitions, transparent limitations, and exercises you can repeat—not promises of easy returns.
Follow Trade Feeld
Frequently asked questions
Sources & further reading
Educational content only, not financial advice. Trading involves risk of loss.
Trade these setups live
Get the same signals our research desk uses — entries, stops, and targets in real time.
Gain instant accessKeep reading
How Companies Actually Make Money: The Core of Fundamental Analysis
Understanding the primary revenue models and cost structures that drive corporate profitability is the first step in fundamental analysis.
What Are Financial Statements? A Beginner's Guide to Corporate Data
Financial statements are the official records of a company's financial activities, providing a snapshot of its health and performance.
Comments(0)
Discuss the article and share your tips.